DoorDash Accident Coverage Checker
Select your status at the moment of the accident to see which insurance policies apply.
Current Insurance Scenario
You’re mid-shift, the app is humming with orders, and suddenly-crunch. Your bumper meets another car. For most people, this triggers a flurry of calls to personal insurers. But for a DoorDash driver, the situation is far more complex because you aren’t just driving; you are working. The question isn't just "who pays?" but "which policy applies when?" This distinction determines whether you walk away with zero out-of-pocket costs or face thousands in repairs.
The Critical Timing: When Are You Actually Covered?
Here is the biggest misconception among new drivers: DoorDash does not cover you 100% of the time you have the app open. Their insurance policy only kicks in during specific windows. If you crash while waiting for your first order after opening the app, you might think you’re covered. You aren’t. That period is known as Period 1, where you are logged in but haven’t accepted a delivery yet. During this phase, DoorDash provides limited contingent liability coverage, which usually only activates if your personal auto insurance denies the claim. It’s a safety net, not a primary shield.
The real protection begins at Period 2: when you accept a delivery request. From the moment you tap "Accept" until you mark the order as delivered, DoorDash’s commercial insurance takes over. This includes $1 million in third-party liability and uninsured motorist coverage. If you hit someone else’s car during this window, their repair bills fall on DoorDash’s insurer, not yours. This is why timing is everything. One tap changes your financial risk profile entirely.
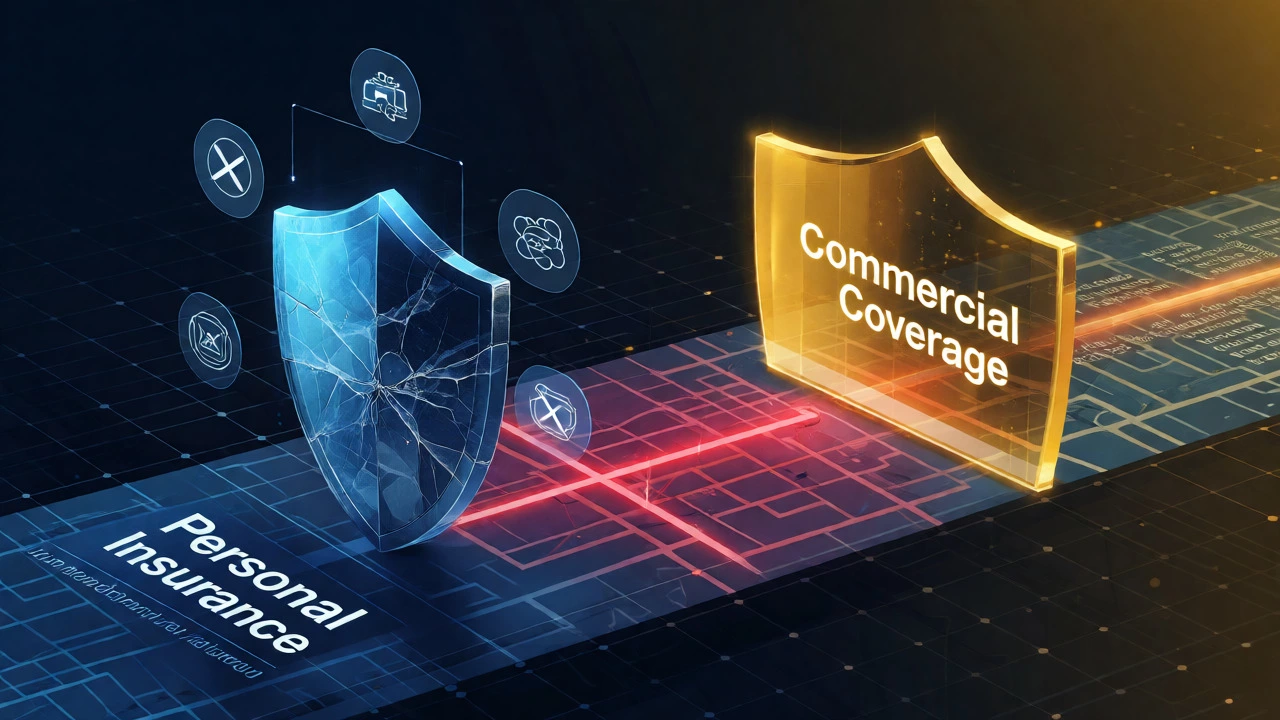
Your Personal Policy vs. Commercial Coverage
Most personal auto policies explicitly exclude coverage for vehicles used for "hire" or "delivery." If you crash during Period 1 (logged in, no order) and your personal insurer finds out you were working, they can deny your claim and even cancel your policy. This leaves you personally liable for damages. Conversely, if you crash during Period 2, DoorDash’s policy acts as the primary payer. However, there is a catch: comprehensive and collision coverage for your own vehicle is rarely provided by DoorDash. They cover damage you do to others, but not necessarily damage to your own car.
| Coverage Type | Period 1: Logged In, No Order | Period 2: En Route/Delivering |
|---|---|---|
| Third-Party Liability | Contingent (only if personal denies) | Primary ($1M limit) |
| Uninsured Motorist | Not typically covered | Covered up to $1M |
| Collision (Your Car) | Personal Policy (if valid) | Personal Policy (if valid) |
| Comprehensive (Theft/Fire) | Personal Policy (if valid) | Personal Policy (if valid) |
What to Do Immediately After a Crash
Panic is normal, but protocol saves money. First, check for injuries and call emergency services if needed. Then, document everything. Take photos of all vehicles involved, license plates, and the surrounding area. Crucially, you must report the accident through the Dasher app within 24 hours. Use the "Report an Incident" feature. Failing to do this can void any potential claim assistance from DoorDash. Even if the other driver says "it's fine," file the report. Minor dents often hide structural issues that cost hundreds later.
Do not admit fault at the scene. Say something neutral like, "I’m sorry this happened," rather than "My bad, I didn't see you." Let the insurers sort out liability based on police reports and dashcam footage. If you have a dashcam, save that footage immediately. It is the single best piece of evidence you can provide to protect yourself against false claims.
The Gap in Protection: Damage to Your Own Vehicle
This is where many drivers get burned. DoorDash’s insurance covers what you hit, not what hits you. If you rear-end a luxury SUV, DoorDash pays for the SUV’s bumper. If the SUV stops short and you hit it, who pays for your bumper? Usually, it’s your personal collision coverage. But remember, your personal insurer might argue you were using the car for business. If they deny the claim because you lacked a commercial endorsement, you pay out of pocket.
To fix this gap, you need a commercial auto policy or a rideshare/delivery endorsement on your personal plan. Major insurers like State Farm, Allstate, and GEICO offer these add-ons. They bridge the gap between personal use and active delivery work. Without this, you are essentially self-insuring your own vehicle during every shift. A $50/month endorsement is cheap insurance compared to a $3,000 deductible denial.
Injuries and Workers' Compensation
If you are injured in an accident, do not expect workers' compensation benefits. As an independent contractor, you are not an employee. DoorDash does not provide health insurance or paid sick leave for injuries sustained on the job. Your medical bills will likely go to your personal health insurance provider. However, if the other driver was at fault, you may be able to pursue a personal injury claim against their liability insurance. This process is slow and often requires legal help, so keep all medical records and receipts meticulously.
Consider purchasing an accident health policy specifically for gig workers. These policies pay out a fixed amount for broken bones, concussions, or hospital visits, regardless of who was at fault. It fills the income gap while you recover. Since you don’t get paid when you’re not driving, a few weeks off due to a whiplash injury can hurt financially. An accident policy mitigates that risk.
Frequently Asked Questions
Does DoorDash cover my car if I crash while delivering?
No, DoorDash’s insurance primarily covers third-party liability (damage you cause to others). Damage to your own vehicle is typically covered by your personal collision insurance, provided your policy allows for commercial use. If your personal insurer denies the claim because you were working, you may have to pay for repairs out of pocket unless you have a specific commercial endorsement.
What happens if I crash before accepting an order?
If you are logged into the app but haven't accepted a delivery, you are in "Period 1." DoorDash provides contingent liability coverage, which only applies if your personal auto insurance refuses to cover the accident. If your personal insurer accepts the claim, DoorDash’s coverage does not activate. This makes having a solid personal policy crucial during idle time.
Will my personal insurance cancel me for doing DoorDash?
It depends on your provider. Many standard personal auto policies exclude coverage for vehicles used for hire or delivery. If you crash and fail to disclose that you were working, your insurer could deny the claim or cancel your policy. To stay safe, inform your insurer about your gig work and ask for a commercial endorsement or rideshare/delivery add-on.
How long do I have to report an accident to DoorDash?
You should report any accident through the Dasher app within 24 hours of the incident. While some sources say 7 days, reporting immediately ensures that DoorDash can coordinate with their insurance partner and preserves your eligibility for any contingent coverage. Delayed reporting can complicate claims and lead to denials.
Do I need commercial insurance for DoorDash?
Strictly speaking, no, you don't need a full commercial truck policy. However, you do need a personal policy that permits delivery activities or a specific commercial endorsement. Standard personal policies often prohibit "livery" or "hire" use. Operating without proper coverage risks claim denials and policy cancellation.